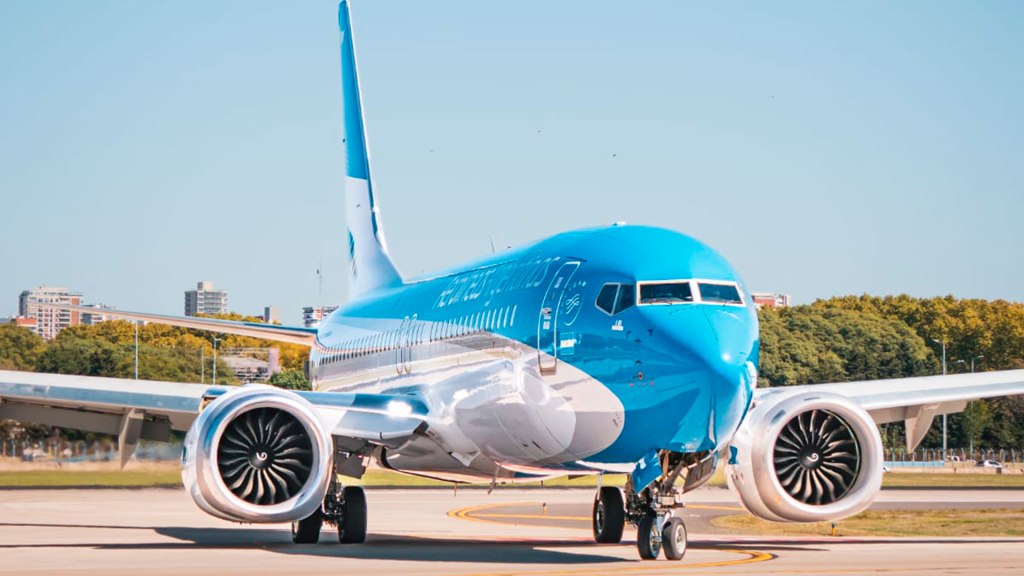
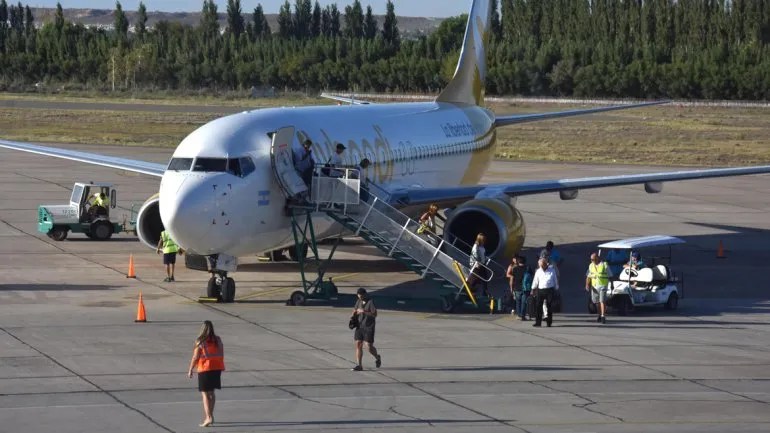Una asamblea de trabajadores en Aeroparque provocó demoras en el despacho de equipajes debido a un paro del Personal Aeronáutico. Pasajeros expresaron su indignación a través de las redes sociales debido a la larga espera. El hecho ocurrió este Sábado 10/12 por la noche y se trató de una medida sorpresiva. Trabajadores anunciaron asamblea en horario laboral, de manera que no se despacharon maletas y numerosos usuarios debieron esperar a que finalizara la reunión para poder retirarse del aeropuerto. A través de las redes sociales, los afectados no tardaron en dar a conocer la situación y expresar su enojo por la larga espera. Durante el Sábado por la noche, pasajeros de distintas aerolíneas se vieron alcanzados por una medida de fuerza sorpresiva que llevaron a cabo los trabajadores del sector vinculado a la distribución de equipaje. Por tal motivo, muchos esperaron sentados sobre la cinta transportadora de maletas y entre medio de aplausos y gritos.
Según trascendió, las demoras llegaron a ser de hasta tres horas mientras que algunos pasajeros debieron permanecer sobre el avión durante más de una hora. Tal situación generó fuertes reclamos por parte de quienes deseaban descender en su lugar de destino. A través de las redes sociales, los pasajeros compartieron distintas imágenes y expresaron su indignación por la medida gremial que llevó a cabo Intercargo. Por caso, una usuaria de Twitter remarcó que las personas se convirtieron en “rehenes de la prepotencia sindical”.
Dado que no había personal disponible para la carga y descarga de equipaje, los pasajeros debieron esperar y mientras lo hicieron; usaron el tiempo para expresar su indignación a través de una serie de videos filmados en la sala de espera del equipaje. A raíz de la medida de fuerza, los vuelos de JetSMART Airlines con destino a Bariloche y el que tenían hacia Tucumán, fueron los demorados a causa de la medida de fuerza. Por tal motivo, se vieron afectados 155 pasajeros que no pudieron concretar su viaje en los tiempos habituales.
Delays at Aeroparque
Assembly generates delays in flights 11/12
An assembly of workers at Jorge Newbery Airport/AEP caused delays in baggage dispatch due to a strike by Aeronautical Personnel. Passengers expressed their outrage through social networks due to the long wait. The event occurred this Saturday 10/12 at night and it was a surprise measure. Workers announced a meeting during working hours, so no bags were dispatched and many users had to wait for the meeting to end before they could leave the airport. Through social networks, those affected did not take long to publicize the situation and express their anger at the long wait. During Saturday night, passengers from different airlines were affected by a surprise force measure carried out by workers in the sector linked to the distribution of luggage. For this reason, many waited sitting on the luggage conveyor belt and amid applause and shouts.
According to reports, the delays were up to three hours while some passengers had to remain on the plane for more than an hour. This situation generated strong claims from those who wanted to descend at their destination. Through social networks, passengers shared different images and expressed their indignation at the union measure carried out by Intercargo. For example, a Twitter user remarked that people became «hostages of union arrogance».
Since there were no staff available to load and unload luggage, the passengers had to wait and while they did so; they used the time to express their outrage through a series of videos filmed in the baggage hold. As a result of the measure of force, the JetSMART Airlines flights to Bariloche and the one they had to Tucumán were delayed due to the measure of force. For this reason, 155 passengers who were unable to complete their trip in the usual times were affected.
PUBLISHER: Airgways.com DBk: Airgways.com AW-POST: 202212111451AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
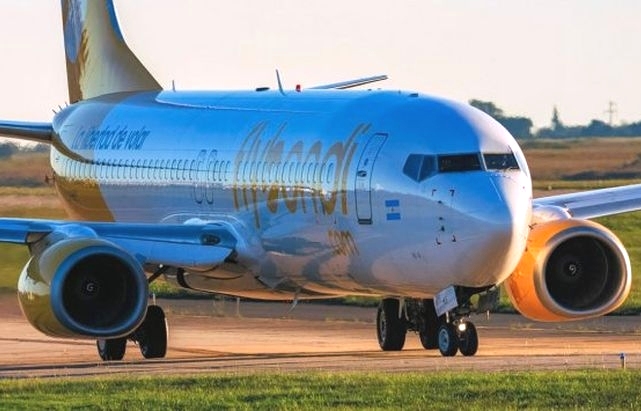
La aerolínea low cost Flybondi anunció que aumentará las frecuencias Buenos Aires/AEP—Neuquén/NQN y Córdoba/COR—Neuquén/NQN. En plena reactivación pos-pandemia, la compañía de presupuesto argentina sumará más vuelos para la Provincia de Neuquén. En principio incrementará la frecuencia entre Buenos Aires y Neuquén de siete a trece frecuencias semanales (13Frq/S). Mientras tanto, fortalecerá su ruta interprovincial federal Córdoba/COR—Neuquén/NQN, incrementando de un vuelo por semana a tres frecuencias semanales (3Frq/S).
De esta manera, la compañía aérea finaliza su plan inicial de crecimiento e inversión en el que se propuso duplicar su flota, su oferta y la cantidad de pasajeros transportados. Con la llegada de los nuevos aviones, también sumará frecuencias para rutas internacionales. El anuncio se dio a conocer a dos días de la llegada del décimo Boeing 737-800 NG con capacidad para 189 personas. Tras la nueva incorporación, Flybondi posee una flota de diez aeronaves, concluyendo el 2022 con el arribo de dos Boeing 737-800 adicionales, superando de esta manera el plan original para terminar el 2022 con una flota total de doce unidades.
Perspectivas Flybondi
Flybondi proyectará lanzar al mercado de leasing una búsqueda de por lo menos cinco aviones más Boeing 737-800 para sumar durante 2023. Durante este último año, la primera aerolínea low cost en Argentina incorporó más de 500 empleados y generó más de 13.500 empleos indirectos en todo el territorio argentino. También aumentó sus frecuencias a toda sus rutas nacionales e internacionales. En esa línea, amplió la conectividad con el sur, incorporando cuatro destinos de cabotaje: Ushuaia, Puerto Madryn, El Calafate y Comodoro Rivadavia. En la actualidad ya vuela a 15 provincias, a diecisiete destinos nacionales y dos destinos internacionales.
Flybondi increases Frq Neuquén
Incorporates more frequencies to Neuquén/NQN
The low cost Flybondi airline announced that the Buenos Aires/AEP—Neuquén/NQN and Córdoba/COR—Neuquén/NQN frequencies will increase. In full post-pandemic reactivation, the Argentine Budget Company will add more flights to the province of Neuquén. In principle, the frequency between Buenos Aires and Neuquén from seven to thirteen weekly frequencies (13Frq/S) will increase. Meanwhile, it will strengthen its Federal Interprovincial Route Córdoba/COR—Neuquén/NQN, increasing a flight per week to three weekly frequencies (3Frq/S).
In this way, the airline ends its initial growth and investment plan in which it proposed to double its fleet, its offer and the number of passengers transported. With the arrival of the new aircraft, it will also add frequencies for international routes. The announcement was released two days after the arrival of the tenth Boeing 737-800 NG with capacity for 189 people. After the new incorporation, Flybondi has a fleet of ten aircraft, concluding 2022 with the arrival of two additional Boeing 737-800, thus exceeding the original plan to finish 2022 with a total fleet of twelve units.
Flybondi perspectives
Flybondi will project to launch a search for at least five more Boeing 737-800 aircraft to add during 2023. During this last year, the first low cost airline in Argentina incorporated more than 500 employees and generated more than 13,500 indirect jobs in the entire Argentine territory. It also increased its frequencies to all its national and international routes. In that line, he expanded connectivity with the South, incorporating four cabotage destinations: Ushuaia, Puerto Madryn, El Calafate and Comodoro Rivadavia. At present it already flies to 15 provinces, to seventeen national destinations and two international destinations.
PUBLISHER: Airgways.com DBk: Flybondi.com / Airgways.com AW-POST: 202212101455AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
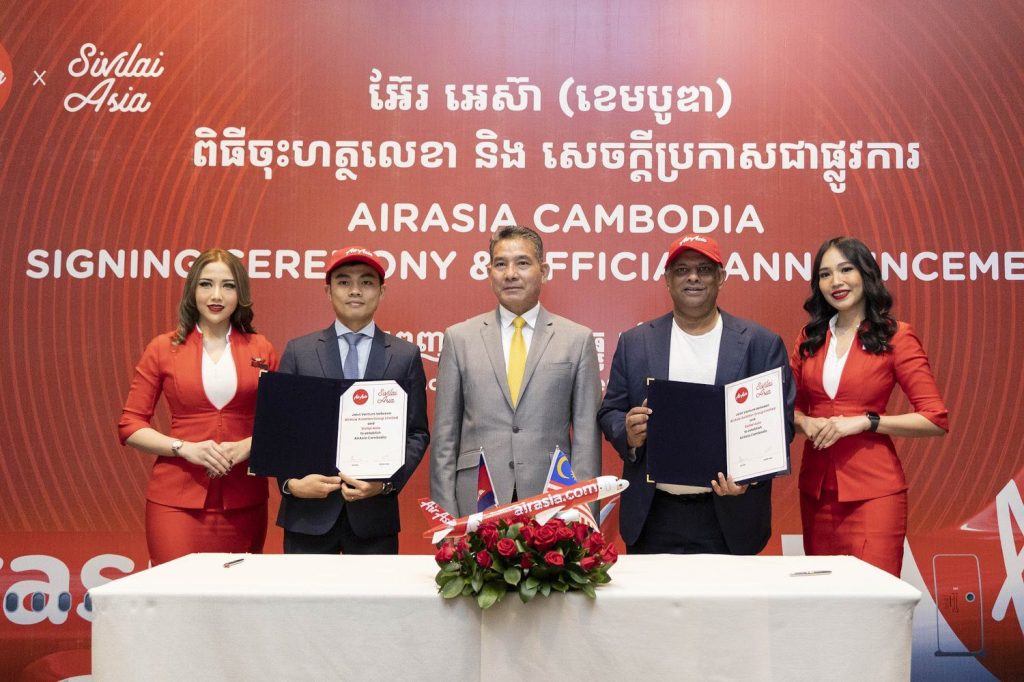
AirAsia lanzará aerolínea de bajo costo en Camboya
AirAsia Aviation Group anunció el Viernes 09/12 una nueva aerolínea conjunta con Sivilai Asia, con sede en Camboya, para lanzar una nueva aerolínea de bajo costo denominada AirAsia Cambodia. La aerolínea, en la que AirAsia será el socio mayoritario, espera comenzar a operar a fines de 2023. Camboya es el quinto destino del sudeste asiático en el que AirAsia incursionará después de Malasia, Indonesia, Tailandia y Filipinas. En declaraciones a los medios, Tony Fernandes, CEO de Capital A, la empresa matriz de AirAsia, dijo que todas las futuras aerolíneas del grupo tendrían su sede en la región, ya que esta es un área que conocen mejor y tienen una fuerte presencia de marca. En 2020, el grupo de aviación cerró las operaciones de AirAsia Japan y el mes pasado la compañía anunció que había vendido su participación restante del 16,67 por ciento en AirAsia India a Air India, propiedad de Tatas.
AirAsia planea tocar los niveles anteriores a Covid para el segundo trimestre de 2023 y, al más puro estilo de Tony Fernandes, el CEO de Capital A dijo que confía en que AirAsia Cambodia sea rentable desde el principio. «Camboya es un mercado que nos es familiar y donde tenemos una infraestructura profunda», dijo Tony Fernandes.
AirAsia Aviation Group es la aerolínea extranjera más grande y el segundo grupo de aerolíneas más grande que opera en Camboya en términos de capacidad, según el CEO del grupo, Bo Lingam. Antes de la pandemia, AirAsia operaba 90 vuelos semanales desde Malasia y Tailandia a Camboya y actualmente vuela alrededor de 49 vuelos semanales. «El valor de la red de AirAsia es un activo insuperable; será otra bandera de amplia conectividad en Camboya y en la región, a saber, China, India y el norte de Asia», dijo Tony Fernandes.
Actualmente, no hay vuelos directos entre India y Camboya. En respuesta a informes anteriores de una fusión propuesta de AirAsia y AirAsia X, Fernandes había aclarado el lunes que el grupo propuso formar un grupo de aviación separado que comprendiera todas sus aerolíneas.
Startup AirAsia Cambodia
AirAsia to launch low-cost airline in Cambodia
AirAsia Aviation Group announced on Friday 09/12 a new joint airline with Cambodia-based Sivilai Asia to launch a new low-cost airline named AirAsia Cambodia. The airline, in which AirAsia will be the majority partner, expects to start operations by the end of 2023. Cambodia is the fifth Southeast Asian destination AirAsia will enter after Malaysia, Indonesia, Thailand and the Philippines. Speaking to the media, Tony Fernandes, CEO of Capital A, AirAsia’s parent company, said that all future airlines in the group would be based in the region as this is an area they know best and have a strong airline presence. brand. In 2020, the aviation group closed operations of AirAsia Japan and last month the company announced it had sold its remaining 16.67 percent stake in AirAsia India to Tatas-owned Air India.
AirAsia plans to touch pre-Covid levels by the second quarter of 2023 and, in true Tony Fernandes fashion, the CEO of Capital A said he is confident AirAsia Cambodia will be profitable from the start. «Cambodia is a market that is familiar to us and where we have a deep infrastructure», Tony Fernandes said.
AirAsia Aviation Group is the largest foreign airline and the second largest airline group operating in Cambodia in terms of capacity, according to the group’s CEO, Bo Lingam. Before the pandemic, AirAsia operated 90 weekly flights from Malaysia and Thailand to Cambodia and currently flies around 49 weekly flights. «The value of AirAsia’s network is an unbeatable asset; it will be another flagship for broad connectivity in Cambodia and in the region, namely China, India and North Asia», said Tony Fernandes.
Currently, there are no direct flights between India and Cambodia. Responding to earlier reports of a proposed merger of AirAsia and AirAsia X, Fernandes had clarified on Monday that the group proposed to form a separate aviation group comprising all of its airlines.
ចាប់ផ្តើមក្រុមហ៊ុន AirAsia Cambodia
បើកដំណើរការក្រុមហ៊ុនអាកាសចរណ៍ AirAsia Cambodia
ក្រុមហ៊ុនអាកាសចរណ៍ AirAsia Aviation Group បានប្រកាសនៅថ្ងៃសុក្រ ទី 09/12 នូវក្រុមហ៊ុនអាកាសចរណ៍រួមគ្នាថ្មីមួយជាមួយក្រុមហ៊ុនអាកាសចរណ៍ Sivilai Asia ដែលមានមូលដ្ឋាននៅប្រទេសកម្ពុជា ដើម្បីចាប់ផ្តើមក្រុមហ៊ុនអាកាសចរណ៍តម្លៃទាបថ្មីមួយដែលមានឈ្មោះថា AirAsia Cambodia ។ ក្រុមហ៊ុនអាកាសចរណ៍ដែល AirAsia នឹងក្លាយជាដៃគូភាគច្រើន រំពឹងថានឹងចាប់ផ្តើមប្រតិបត្តិការនៅចុងឆ្នាំ 2023។ កម្ពុជាជាគោលដៅអាស៊ីអាគ្នេយ៍ទីប្រាំដែល AirAsia នឹងចូលបន្ទាប់ពីម៉ាឡេស៊ី ឥណ្ឌូនេស៊ី ថៃ និងហ្វីលីពីន។ ថ្លែងទៅកាន់ប្រព័ន្ធផ្សព្វផ្សាយ លោក Tony Fernandes នាយកប្រតិបត្តិនៃក្រុមហ៊ុន Capital A ដែលជាក្រុមហ៊ុនមេរបស់ AirAsia បាននិយាយថា ក្រុមហ៊ុនអាកាសចរណ៍នាពេលអនាគតទាំងអស់នៅក្នុងក្រុមនឹងមានមូលដ្ឋាននៅក្នុងតំបន់ ព្រោះនេះជាតំបន់ដែលពួកគេស្គាល់ច្បាស់បំផុត និងមានវត្តមានក្រុមហ៊ុនអាកាសចរណ៍ខ្លាំងម៉ាកយីហោ។ ក្នុងឆ្នាំ 2020 ក្រុមអាកាសចរណ៍បានបិទប្រតិបត្តិការរបស់ក្រុមហ៊ុន AirAsia Japan ហើយកាលពីខែមុនក្រុមហ៊ុនបានប្រកាសថាខ្លួនបានលក់ភាគហ៊ុន 16.67 ភាគរយដែលនៅសល់របស់ខ្លួននៅក្នុង AirAsia India ទៅឱ្យក្រុមហ៊ុន Tatas ដែលគ្រប់គ្រងដោយក្រុមហ៊ុន Air India ។
ក្រុមហ៊ុន AirAsia គ្រោងនឹងឈានដល់កម្រិតមុនកូវីដនៅត្រឹមត្រីមាសទី 2 ឆ្នាំ 2023 ហើយតាមពិតលោក Tony Fernandes នាយកប្រតិបត្តិនៃក្រុមហ៊ុន Capital A បាននិយាយថាលោកមានទំនុកចិត្តថា AirAsia Cambodia នឹងទទួលបានប្រាក់ចំណេញចាប់ពីពេលចាប់ផ្តើម។ លោក Tony Fernandes បានមានប្រសាសន៍ថា “ប្រទេសកម្ពុជាគឺជាទីផ្សារដែលធ្លាប់ស្គាល់យើង ហើយជាកន្លែងដែលយើងមានហេដ្ឋារចនាសម្ព័ន្ធដ៏ជ្រៅ»។
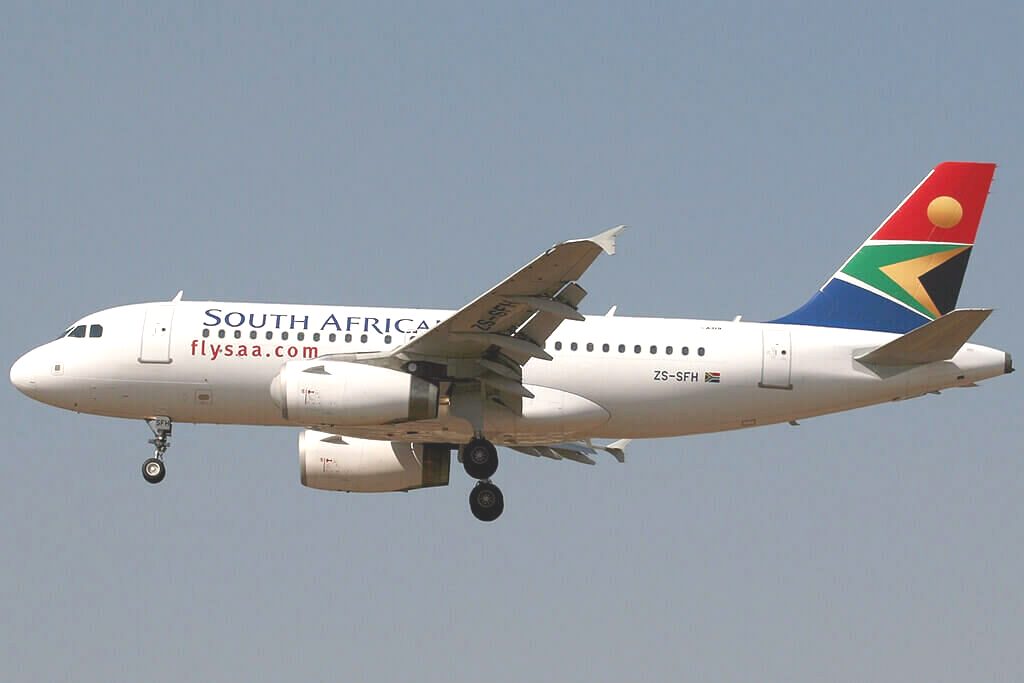
South African Airways restablece conexión a Windhoek
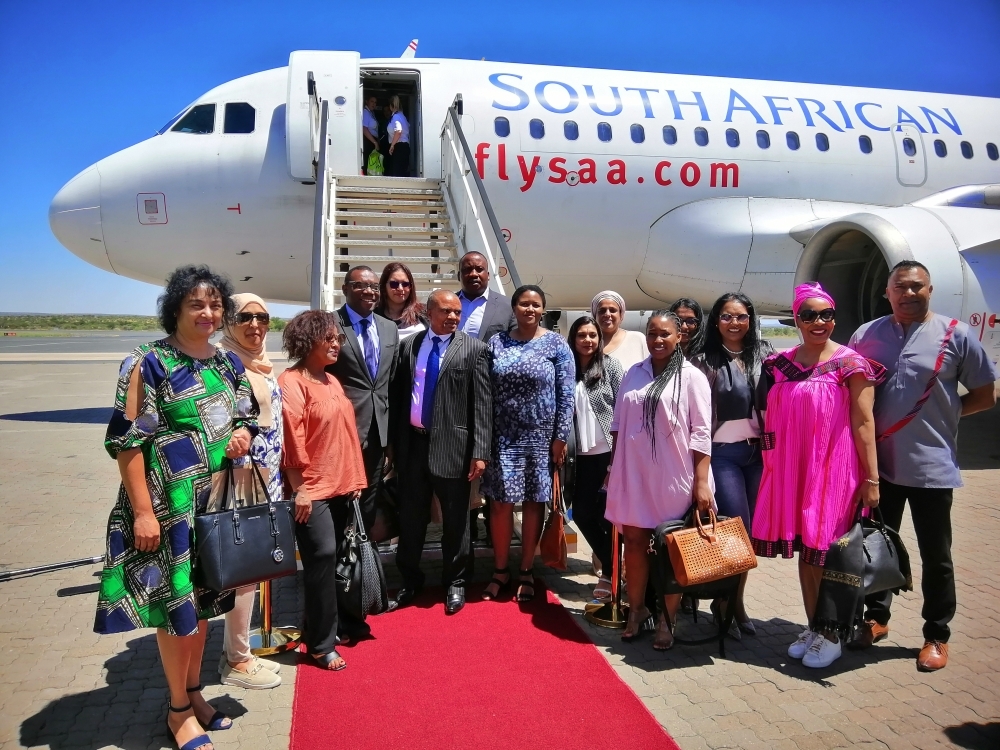
South African Airways (SAA) a restablecido sus operaciones en Namibia al Aeropuerto Internacional Hosea Kutako/WDH, a medida que se revitaliza la industria de la aviación. SAA ofrecerá dos frecuencias diarias (2Frq/D) Johannesburgo/JNB—Windhoek. La Compañía de Aeropuertos de Namibia (NAC) ha dado la bienvenida a la aerolíneas tras un proceso de retracción de mercado generado por la crisis sanitaria mundial.
South African Airways aterrizó el Jueves 08/12, tras haber abandonado el país por última vez en Marzo de 2019 y con su regreso se unirá a otras aerolíneas que hacen escala en WDH que incluyen, Qatar Airways, TAAG Angola Airlines, Ethiopian Airlines, Eurowings, Air Link y FlyNamibia Airline. «En NAC estamos entusiasmados con el regreso de SAA porque significa más opciones para visitantes y viajeros», dijo Dan Kamati, Director de NAC.
Dando la bienvenida al desarrollo, el Viceministro de Transporte de Namibia, Veikko Nekundi, dijo en un comunicado que el relanzamiento del servicio de SAA entre Windhoek y Johannesburgo fortalecerá el comercio y el turismo al tiempo que fomentará los lazos existentes en todos los frentes. «Namibia forma parte del Mercado Único Africano de Transporte Aéreo (SAATM); una iniciativa de la Unión Africana para crear un mercado único unificado de transporte aéreo en África a fin de promover la liberalización de la aviación civil en África y dar un impulso al programa de integración económica del continente. SAATM garantizará que la aviación desempeñe su papel en la conexión de África, promoviendo su integración social, económica y política, e impulsando el comercio intra-africano», dijo Veikko Nekundi.
La perspectiva de SAA tiene previsto introducir nuevas rutas a las Cataratas Victoria en Zimbabwe, y un horario especial para Ggeberha desde el Aeropuerto Internacional de Johannesburgo/OR Tambo/JNB.
South African returns to Namibia
South African Airways restores connection to Windhoek
South African Airways (SAA) has reestablished its operations in Namibia at Hosea Kutako International Airport/WDH, as the aviation industry is revitalized. SAA will offer two daily frequencies (2Frq/D) Johannesburg/JNB—Windhoek. The Namibia Airports Company (NAC) has welcomed the airlines after a process of market retraction generated by the global health crisis.
South African Airways landed on Thursday 08/12, having last left the country in March 2019 and upon its return will join other airlines that call at WDH including Qatar Airways, TAAG Angola Airlines, Ethiopian Airlines, Eurowings, Air Link and FlyNamibia Airline. «We at NAC are excited about the return of SAA because it means more options for visitors and travelers», said Dan Kamati, Director of NAC.
Welcoming the development, Namibian Deputy Transport Minister Veikko Nekundi said in a statement that the relaunch of SAA’s service between Windhoek and Johannesburg will strengthen trade and tourism while fostering existing ties on all fronts. «Namibia is part of the Single African Air Transport Market (SAATM); an initiative of the African Union to create a single unified air transport market in Africa in order to promote the liberalization of civil aviation in Africa and give impetus to the program of economic integration of the continent. SAATM will ensure that aviation plays its role in connecting Africa, promoting its social, economic and political integration, and boosting intra-African trade», said Veikko Nekundi.
The SAA outlook plans to introduce new routes to Victoria Falls in Zimbabwe, and a special schedule for Ggeberha from Johannesburg International Airport/OR Tambo/JNB.
PUBLISHER: Airgways.com DBk: Flysaa.com / Airports.com.na / Airgways.com AW-POST: 202212101257AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
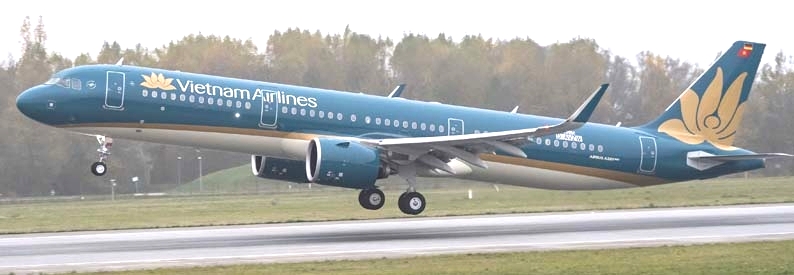
Vietnam Airlines reanuda vuelos a China después de 3 años
Vietnam Airlines ha restablecido los vuelos comerciales a la República Popular de China, con la primera de las tres rutas restablecidas por la aerolína vietnamita. Tras los constantes anuncios de restricciones, China ha sido un mercado difícil de volver a ingresar a medida que los operadores buscan recuperarse de la pandemia de Coronavirus. Una flexibilización de las reglas ha permitido a las aerolíneas retornar de manera sencible a algunos destinos, aunque con las prrecauciones del caso.
La primera ruta que la aerolínea restablecerá enlazará el Aeropuerto Tan Son Nhat International/SGN de la ciudad de Ho Chi Minh hasta Guangzhou Baiyun International/CAN. El primer vuelo VN502 despegó a las 10:09 hs del 09/12, reanudando la conexión interrumpida el 1 de Febrero de 2020 por las restricciones a los vuelos por la crisis sanitaria mundial.
«A medida que China ha aliviado sus restricciones COVID-19, Vietnam Airlines ha reabierto algunas de sus rutas entre los dos países para satisfacer la demanda de viajes», expresó Vietnam Airlines.
Perspectivas chinas
La aerolínea ha anunciado que incrementará los servicios próximamente empleando aeronaves Airbus A321NEO. Además, a partir del Lunes 12/12 se reanudará el servicio entre el Aeropuerto Internacional Nội Bài/HAN de Hanoi y el Aeropuerto Internacional de Shanghai Pudong/PVG, con dos frecuencias semanales (2Frq/S) semana los Lunes y Viernes empleando el A3231NEO en lugar del A350.
El restablecimiento de las operaciones de Vietnam Airlines ha estado planificándose minuciosamente, debido a que el mercado chino en Vietnam representa un importante tráfico de turistas alcanzando unos 4,8 millones en 2019, como así también la residencia de alrededor de más de 35.000 ciudadanos en China.
Vietnam returns to China
Vietnam Airlines resumes flights to China after 3 years
Vietnam Airlines has restored commercial flights to the People’s Republic of China, with the first of three routes restored by the Vietnamese airline. Following constant announcements of restrictions, China has been a difficult market to re-enter as traders look to recover from the Coronavirus pandemic. A relaxation of the rules has allowed airlines to easily return to some destinations, although with the necessary precautions.
The first route the airline will reinstate will link Ho Chi Minh City’s Tan Son Nhat International/SGN Airport to Guangzhou Baiyun International/CAN. The first flight VN502 took off at 10:09 a.m. on 12/09, resuming the connection interrupted on February 1, 2020 due to flight restrictions due to the global health crisis.
«As China has eased its COVID-19 restrictions, Vietnam Airlines has reopened some of its routes between the two countries to meet travel demand», Vietnam Airlines said.
Chinese perspectives
The airline has announced that it will soon increase services using Airbus A321NEO aircraft. In addition, as of Monday 12/12, the service between Hanoi Nội Bài/HAN International Airport and Shanghai Pudong/PVG International Airport will resume, with two weekly frequencies (2Frq/S) week on Mondays and Fridays using the A3231NEO instead of the A350.
The reestablishment of the operations of Vietnam Airlines has been carefully planned, due to the fact that the Chinese market in Vietnam represents significant tourist traffic, reaching some 4.8 million in 2019, as well as the residence of around more than 35,000 citizens in China.
PUBLISHER: Airgways.com DBk: Vietnamairlines.com / Airgways.com AW-POST: 202212091203AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
BA Euroflyer recibe certificado AOC Startup con base en Aeropuerto London/Gatwick
British Airways irrumpe en el mercado low cost con la filial BA Euroflyer. British Airways vuelve a volar desde London/Gatwick a la mayor parte de los destinos domésticos y vacacionales europeos, con una flota de Airbus A320. Es la rama más deficitaria de la compañía que la dirección dijo que iba a cerrar si tenía que mantenerla con el marco laboral de la matriz. Pero los empleados aceptaron que sus condiciones fueran bajo las condiciones laborales de una compañía de presupuesto aérea por lo que British Airways decidió crear una filial para esa flota, con condiciones propias, pero manteniendo el servicio de la marca.
El Lunes 05/12 la Autoridad de Aviación Civil (CAA) del Reino Unido ha otorgado el Certificado de Operador Aéreo (AOC) a la nueva aerolínea. La aerolínea se llamará British Airways Euroflyer y será comparable a British Airways CityFlyer, que agrupa los aviones que operan desde London City. Esta nueva filial se denominaría Euroflyer, pero ha mudado de nombre a BA Euroflyer.
la nueva filial no tendrá muchos cambios visibles, pero durante los próximos seis meses, diecinueve aviones que son de British Airways y tienen base en London/Gatwick serán traspasados jurídicamente a la nueva aerolínea, junto con su plantilla de empleados. Pero los cambios más significativos de BA Euroflyer se establecen en los nuevos contratos laborales en inferiores condiciones que los de London/Heathrow. Incluso también hay algunos aviones de British Airways, de largo radio, en London/Gatwick, que siguen siendo de Heathrow, con sus condiciones.
La plantilla de vuelos europeos, en cambio, tendrá salarios comparables con aerolíneas de la talla de la británica Easyjet. Una de las razones por la que la existencia de la aerolínea de presupuesto ha venido a su existencia es traducida en los términos de poder competir en un mercado low cost cada vez más significativo. La operación del acuerdo de BA Euroflyer concluirá totalmente para el verano europeo al terminar toda la documentación requerida, mientras que el usuario del transporte aéreo tendrá beneficios de volar en una aerolínea de bajos precios.
British Airways Euroflyer is born
BA Euroflyer receives AOC certificate Startup based in London/Gatwick Airport
British Airways breaks into the low cost market with the subsidiary BA Euroflyer. British Airways once again flies from London/Gatwick to most European domestic and holiday destinations, with a fleet of Airbus A320s. It is the most loss-making arm of the company that management said it would shut down if it had to keep it within the parent framework. But the employees accepted that their conditions were under the working conditions of an airline budget company, so British Airways decided to create a subsidiary for that fleet, with its own conditions, but maintaining the brand’s service.
On Monday 05/12 the Civil Aviation Authority (CAA) of the United Kingdom has granted the Air Operator Certificate (AOC) to the new airline. The airline will be called British Airways Euroflyer and will be comparable to British Airways CityFlyer, which groups planes operating from London City. This new subsidiary would be called Euroflyer, but has changed its name to BA Euroflyer.
The new subsidiary won’t have many visible changes, but over the next six months, nineteen London/Gatwick-based British Airways aircraft will be legally transferred to the new airline, along with their staff. But the most significant changes at BA Euroflyer are established in the new employment contracts under lower conditions than those of London/Heathrow. There are also some long-haul British Airways planes in London/Gatwick, which are still from Heathrow, with their conditions.
The staff of European flights, on the other hand, will have salaries comparable with airlines of the stature of the British Easyjet. One of the reasons why the existence of the budget airline has come into existence is translated in terms of being able to compete in an increasingly significant low cost market. The operation of the BA Euroflyer deal will be fully concluded by the European summer upon completion of all required documentation, while the air transport user will have benefits of flying on a low-fare airline.
PUBLISHER: Airgways.com DBk: Britishairways.com / Airgways.com AW-POST: 202212081424AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
Aerolíneas Argentinas avanzar combustible sustentable en 2023
Aerolíneas Argentinas tiene previsto establecer una agenda integral para acceder al Combustible de Aviación Sostenible (SAF) mediante un trabajo conjunto entre organismos estatales y empresas privadas el próximo año, según indicaron hoy fuentes de la compañía. La producción de SAF alcanzará al menos 300 millones de litros en 2022, lo que significa un aumento del 200% respecto de la producción de 2021, que había sido de 100 millones de litros, según los datos suministrados por la Asociación Internacional de Transporte Aéreo (IATA), en un encuentro de periodistas especializados en aviación que se realiza en la sede de IATA en Ginebra. No obstante, hay cálculos optimistas que estiman que la producción total en 2022 podría alcanzar los 450 millones de litros, un escenario que coloca a la industria SAF al borde de un aumento exponencial de la capacidad y la producción hacia un punto de inflexión identificado de 30.000 millones de litros para 2030, con las políticas de apoyo adecuadas.
Las aerolíneas se comprometen a lograr cero emisiones netas de CO2 para 2050 y ven a SAF como un contribuyente clave, y las estimaciones actuales esperan que SAF represente el 65% de la mitigación necesaria para esto, lo que requiere una capacidad de producción de 450 mil millones de litros anuales en 2050. Por eso, Aerolíneas Argentinas viene trabajando firmemente para un presente y un futuro sustentable, y tiene previsto establecer una agenda integral para acceder al SAF en el 2023, mediante el trabajo conjunto entre organismos estatales y empresas privadas, indicaron fuentes de la empresa. «Desarrollamos diferentes proyectos alineados a los Objetivos de Desarrollo Sustentable (ODS) definidos en 2015 por la Organización de las Naciones Unidas, en el marco de la Agenda 2030 sobre el Desarrollo Sostenible. Una oportunidad para que los países y sus sociedades emprendan un nuevo camino en pos de mejorar la vida», expresaron desde la compañía aérea.
Respecto a la reducción de emisiones de CO2 en largo recorrido, Aerolíneas Argentinas introdujo modificaciones en el proceso de carga y ocupación de las bodegas haciéndolo más eficiente y reduciendo el consumo por tonelada transportada. También, las reducciones del consumo tienen relación directa con su Programa de Eficiencia en Combustible (PEC), el cual realiza el seguimiento y análisis de la forma en que se utiliza el combustible en vuelo y el concepto de Free Route Airspace (FRA), que consiste en un sistema de navegación con diferentes puntos de entrada y salida de espacios aéreos con el objetivo de volar directo y mejorar la trayectoria del vuelo en función de la distancia más corta.
Los gobiernos de la región comparten ahora el mismo objetivo para la descarbonización con la aviación, y por ende el interés en el éxito de SAF. «Hubo al menos el triple de la cantidad de SAF en el mercado en 2022 que en 2021. ¡Y las aerolíneas usaron cada gota, incluso a precios muy altos! Si hubiera más disponible, se habría comprado. Eso deja en claro que se trata de un problema de oferta y que las fuerzas del mercado por sí solas son insuficientes para resolverlo. Los gobiernos, que ahora comparten el mismo objetivo neto cero para 2050, deben implementar incentivos de producción integrales para SAF. Es lo que hicieron para lograr una transición exitosa de las economías a fuentes renovables de electricidad. Y es lo que la aviación necesita para descarbonizarse», dijo Willie Walsh, Director General de IATA.
Hasta la fecha se han operado más de 450 000 vuelos comerciales con SAF, y el creciente número de aerolíneas que firman acuerdos de compra con productores envía una señal clara a los mercados de que se necesita SAF en cantidades mayores y, en lo que va de 2022 se firmaron alrededor de 40 acuerdos de compra.
Aerolíneas avanza SAF 2023
Aerolíneas Argentinas Sustainable fuel progress in 2023
Aerolíneas Argentinas plans to establish an integral agenda to access sustainable aviation fuel (SAF) through a joint work between state agencies and private companies next year, company sources indicated today. SAF production will reach at least 300 million liters in 2022, which means a 200% increase compared to the production of 2021, which had been 100 million liters, according to the data provided by the International Air Transport Association (IATA), in a meeting of journalists specialized in aviation that takes place at the IATA headquarters in Geneva. However, there are optimistic calculations that estimate that total production in 2022 could reach 450 million liters, a scenario that places the SAF industry on the edge of an exponential increase in capacity and production towards an identified inflection point of 30,000 Millions of liters by 2030, with appropriate support policies.
Airlines undertake to achieve zero net emissions of CO2 by 2050 and come to SAF as a key taxpayer, and current estimates expect SAF to represent 65% of the mitigation necessary for this, which requires a production capacity of 450 thousand Millions of liters per year in 2050. Therefore, Aerolineas Argentinas has been working firmly for a present and a sustainable future and plans to establish an integral agenda to access the SAF in 2023, through joint work between state agencies and private companies, they said company sources. «We develop different projects aligned to the Sustainable Development Goals (SDGs) defined in 2015 by the United Nations Organization, within the framework of the 2030 Agenda on Sustainable Development. An opportunity for countries and their societies to undertake a new path In order to improve life», they said from the airline.
Regarding the reduction of CO2 emissions on long travel, Aerolíneas Argentinas introduced modifications in the load and occupation process of the wineries making it more efficient and reducing consumption by transported ton. Also, consumption reductions are directly related to their Fuel Efficiency Program (PEC), which performs the monitoring and analysis of the way in which the fuel in flight is used and the concept of Free Route Airspace (FRA), which consists of a navigation system with different points of entry and exit of air spaces with the aim of flying direct and improving the flight trajectory based on the shortest distance.
The governments of the region now share the same objective for decarbonization with aviation, and therefore the interest in the success of SAF. «There was at least triple the amount of SAF in the market in 2022 that in 2021. And the airlines used each drop, even at very high prices! If I had more available, it would have bought. That makes it clear that it is about of an offer problem and that market forces alone are insufficient to solve it. Governments, which now share the same zero net objective by 2050, must implement comprehensive production incentives for SAF. It is what they did to achieve a transition Successful economies to renewable sources of electricity. And it is what aviation needs to decarbonize», said Willie Walsh, IATA General Director.
To date, more than 450,000 commercial flights have been operated with SAF, and the growing number of airlines that sign purchase agreements with producers send a clear signal to the markets that SAF is needed in larger quantities and, so far this goes from 2022 around 40 purchase agreements were signed.
PUBLISHER: Airgways.com DBk: Aerolineas.com / Airgways.com AW-POST: 202212081250AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
Latinoamericanas anuncian pérdidas 2023 Región Norteamérica beneficios 2022-2023
La Asociación Internacional de Transporte Aéreo (IATA) ha informado el conjunto de compañías latinoamericanas terminarán el año 2022 con pérdidas del orden de los US$ 2.000 millones de Dólares, mientras que las proyecciones para el 2023 arrastraría números rojos en valores aproximados en US$ 795 millones, según el organismo que representa a la industria de la aviación comercial.
Las perspectivas de la demanda de pasajeros en Latinoamérica podrían incrementarse en un 9.3% el próximo año 2023, por encima del 6.3% del aumento de la capacidad, indicó la entidad en la presentación de los datos económicos del sector de 2022 y sus proyecciones para 2023. El tráfico latinoamericano de pasajeros ha alcanzado en 2022 un 12.6% por debajo de las cifras de 2019, el año previo a la pandemia, y se espera que el próximo año alcance alrededor de 8.2%, una baja de 4,4%, aunque esto no signifique que las variables de mercado puedan cambiar favorablemente.
De todas las regiones del mundo, Norteamérica es la única donde se han observado beneficios netos del 9.9% en 2022 y se espera que este ritmo de recuperación se mantenga en 2023 con incrementos del orden del 11.4%. Las proyecciones para Estados Unidos y Canadá hacia el 2023 apuntan a recuperar el 97.2% de los niveles prepandemia. Entre las razones de esta recuperación, la IATA destacó que las restricciones de viajes fueron menos severas y largas allí que en cualquier otra parte del mundo, lo que incluyen los viajes internos y los trasatlánticos.
Sobre las aerolíneas europeas, la IATA indicó que perderán US$ 3.100 millones de Dólares en 2022 y volverán a los beneficios en 2023, con ganancias de alrededor de US$ 621 millones de Dólares.
IATA airline projections 2023
Latin Americans announce 2023 losses North America Region Benefits 2022-2023
The International Air Transport Association (IATA) has reported that the group of Latin American companies will end the year 2022 with losses of the order of US$ 2,000 million, while the projections for 2023 would drag red numbers in approximate values of US$ 795 million, according to the body that represents the commercial aviation industry.
The prospects for passenger demand in Latin America could increase by 9.3% next year 2023, above the 6.3% increase in capacity, the entity indicated in the presentation of economic data for the sector for 2022 and its projections for 2023. Latin American passenger traffic has reached 12.6% in 2022 below the figures for 2019, the year before the pandemic, and it is expected that next year it will reach around 8.2%, a drop of 4.4%, although this does not mean that market variables can change favorably.
Of all the regions of the world, North America is the only one where net benefits of 9.9% have been observed in 2022 and this recovery rate is expected to continue in 2023 with increases of the order of 11.4%. Projections for the United States and Canada by 2023 point to a recovery of 97.2% of pre-pandemic levels. Among the reasons for this recovery, IATA highlighted that travel restrictions were less severe and lengthy there than in any other part of the world, including internal and transatlantic travel.
Regarding European airlines, IATA indicated that they will lose US$3.1 billion in 2022 and return to profit in 2023, with earnings of around US$621 million.
PUBLISHER: Airgways.com DBk: Iata.org / Airgways.com AW-POST: 202212081248AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
El programa integral para el desarrollo de la industria del transporte aéreo de la Federación de Rusia hasta 2030 asume que los aviones nacionales ocuparán más del 80% de la flota de las aerolíneas rusas. El Presidente del Gobierno de la Federación de Rusia, Mikhail Mishustin, en una reunión celebrada el 27 de Junio de 2022 con los viceprimeros ministros, anunció la adopción de la Orden del Gobierno de la Federación de Rusia No. 1693-r del 25 de Junio de 2022, que aprobó el Programa Integral para el Desarrollo de la Industria del Transporte Aéreo de la Federación de Rusia hasta 2030. La necesidad de crear dicho documento se declaró durante una reunión sobre el desarrollo del transporte aéreo y la construcción de aviones, presidida por el presidente ruso Vladimir Putin el 31 de Marzo de 2022. Una de las instrucciones posteriores a la reunión sugirió que el Gobierno debería aprobar un programa integral antes del 1 de Junio de 2022 y garantizar su implementación. Según informaron los medios de comunicación, a finales de abril, el Ministerio de Transporte preparó la primera versión del documento, que, sin embargo, fue enviado para su revisión. La segunda versión del programa, enviada al Gobierno a finales de mayo, incluía una previsión que preveía un aumento de los indicadores de volumen.
El Programa Integrado es un documento de 30 páginas que contiene seis anexos. Los autores del programa evaluaron la situación actual en la aviación civil y la industria de la aviación de Rusia, incluida la previsión del volumen de transporte aéreo, realizaron un análisis de la flota de aviones, evaluaron las perspectivas de mantener su aeronavegabilidad, identificaron tipos prioritarios de aviones nacionales, debido a lo cual se actualizará la flota.
Los indicadores volumétricos para el transporte en rutas nacionales e internacionales, según las previsiones, deberían aumentar constantemente. Para 2022, los indicadores se establecen por directiva. Las aerolíneas tendrán que atender a 90 millones de pasajeros en aerolíneas nacionales y 10 millones de pasajeros en aerolíneas internacionales (MVL). Al final del programa, el transporte en VVL debería alcanzar los 104,5 millones de pasajeros, y en MVL 11,6 millones. Por lo tanto, según el documento, la industria restaurará el volumen de tráfico alcanzado en 2021 en 111 millones de pasajeros, para aumentarlo hacia 2029. Las cifras récord de 2019 (128 millones de pasajeros fueron transportados) en el horizonte del programa seguirán siendo insuperables.
La recuperación de los indicadores de volumen en VVL se producirá a un ritmo moderado: del 1,2% en 2023 al 3% en 2030. Para el mercado nacional de transporte aéreo, tales tasas no son típicas: desde principios de siglo, la industria ha mostrado un crecimiento mucho más intensivo o, en tiempos de crisis, una disminución a gran escala. Pero incluso teniendo en cuenta tal repunte, la tasa promedio de aumento en el tráfico de pasajeros fue mayor.
Los autores del documento señalan que la naturaleza del transporte en líneas nacionales no cambiará radicalmente: la configuración de la red de rutas, que se ha desarrollado para 2021-2022, les parece óptima. En total, se sirvieron 4.340 rutas en el VVL en 2021, pero alrededor de 480 de ellas proporcionaron el 95% del tráfico total de pasajeros nacionales. Sin embargo, la pregunta sobre la configuración de la red de rutas sigue abierta: a principios de 2022, la participación del centro de aviación de Moscú era muy grande, por lo que algunos de los pasajeros que viajaban desde los puntos de partida en los Urales o Siberia llegaron a Moscú para continuar el viaje en vuelos internacionales, o en dirección sur. Actualmente, Moscú se está convirtiendo en un destino sin salida: los vuelos a los países de la Unión Europea (UE) se han detenido y es más rentable volar hacia el sur a través de centros regionales.
Estadísticas transporte segundo trimestre
En 2022 los aeropuertos de la capital están perdiendo pasajeros, pero las aero-estaciones siberianas, por el contrario, están aumentando su tráfico de pasajeros. Esta tendencia, si persisten los factores externos actuales, será a largo plazo. Una parte significativa del documento está dedicada a evaluar el estado actual de la flota de aerolíneas rusas y el impacto de las sanciones antirrusas impuestas por varios estados hostiles. En Abril de 2022, la flota de aerolíneas comerciales rusas contaba con 1.287 aviones. La mayor parte de la flota eran buques de pasajeros, había 1.101 de ellos. Otros 84 vehículos son camiones, 42 son aviones de negocios y 60 aviones figuran en la flota en tres instituciones presupuestarias estatales federales, así como en la aerolínea Cosmos y en realidad no participan en el transporte comercial.
Dos tercios de la flota consiste en aviones de fabricación extranjera. Al mismo tiempo, representan alrededor del 95% de la facturación total de pasajeros. Esta distribución es bastante lógica: los aviones extranjeros tienen superioridad en la capacidad total de asientos y se operan en líneas más largas. En abril de 2022, las aerolíneas rusas operaban 120 aviones de larga distancia y 472 de media distancia de producción extranjera, y ni un solo transatlántico nacional de esta dimensión. Pero en los segmentos de corta distancia, máquinas regionales y aviones de líneas aéreas locales, la superioridad estaba del lado de los aviones rusos y soviéticos: 170 aviones nacionales de corta distancia contra 23 automóviles extranjeros, 105 máquinas regionales: 84 extranjeras y 88 aviones de líneas aéreas locales, contra 39.
Un gran número de aviones de las aerolíneas rusas, alrededor de 700 aviones, pertenecen a compañías de arrendamiento extranjeras. La forma más común de transferencia de aeronaves al arrendamiento operativo, en el que al final del contrato de arrendamiento las aeronaves se devuelven al arrendador. Las sanciones impuestas en el primer trimestre de 2022 contra la Federación de Rusia implicaban una prohibición de la venta de aviones y helicópteros, que se aplicaba, entre otras cosas, a los contratos de arrendamiento existentes. Los arrendadores recibieron instrucciones de rescindir los contratos y confiscar las aeronaves en el plazo de un mes hasta finales de Marzo 2022. Además, las sanciones afectaban a dos ámbitos muy sensibles del transporte aéreo: la prohibición del seguro y reaseguro de activos y la prohibición de la prestación de servicios de mantenimiento y reparación de aeronaves, componentes y sistemas. Poco después de la introducción de estas restricciones, los fabricantes de aviones occidentales notificaron a los operadores rusos el cese del apoyo a sus productos y el cese del suministro de piezas de repuesto. En esta situación, aquellas empresas de arrendamiento que no estaban obligadas a romper los acuerdos unilateralmente, violando los acuerdos existentes, exigieron devolver sus activos antes de lo previsto, temiendo una fuerte caída en su valor de mercado.
El transporte aéreo de Rusia se encontró en una situación en la que seguir el ejemplo de Occidente y detener la operación de la mayor parte de la flota de aviones significaba detener las actividades de la industria, poniendo en peligro la conectividad territorial del país y reduciendo drásticamente la movilidad de la población. Obviamente, este enfoque era inaceptable para la aviación civil rusa. Una solución alternativa es negarse a devolver el avión, continuar el cumplimiento de las obligaciones derivadas de los contratos de arrendamiento, aunque en el formato de transferencia de los pagos de arrendamiento en rublos al tipo de cambio actual a cuentas especiales. Fue este enfoque el que aseguró la preservación de la gran mayoría de los aviones en la flota de las transportadoras rusas para Abril de 2022. A su vez, después de que las autoridades de aviación de varios países hostiles decidieran cancelar los certificados de aeronavegabilidad de las aerolíneas rusas, se realizó una transferencia masiva de la flota al registro de aeronaves civiles de la Federación de Rusia, después de lo cual la Agencia Federal de Transporte Aéreo emitió documentos que confirmaban la aeronavegabilidad.
La adopción de medidas de emergencia permitió mantener una capacidad de carga suficiente para que las aerolíneas rusas pudieran continuar operando vuelos en líneas aéreas nacionales, e incluso tenía alguna reserva que puede usarse en el formato de canibalización de la flota. Esto se debe al hecho de que la lista de destinos internacionales disponibles ha disminuido notablemente debido al cierre del espacio aéreo sobre países hostiles. Pero no todos los aviones pueden volar a estados que no apoyan las sanciones: los aviones arrendados pueden ser arrestados en aeropuertos extranjeros.
A pesar de las sanciones, las aerolíneas rusas continúan operando activamente aviones de fabricación extranjera. El Programa Integral presta atención a este problema: en particular, se indica que 241 organizaciones de mantenimiento de aeronaves operan en Rusia, incluidas 34 que recibieron documentos de aprobación en 2022. En cuanto a las reparaciones, se observa que para algunos tipos de aeronaves, el trabajo se realiza exclusivamente en el extranjero. Para los aviones DHC-6 y DHC-8, las soluciones de reparación en Rusia aún están completamente ausentes, y para el Airbus A350 debería aparecer antes de finales de 2022. Las dificultades con la implementación de reparaciones, la obtención de una serie de consumibles, piezas de repuesto, bloques y ensamblajes pueden llevar a la pérdida de aeronavegabilidad de aeronaves individuales. Sin embargo, los autores del documento evalúan este riesgo como moderado: para 2025, al menos el 70% de la composición actual de la flota extranjera debería permanecer en el ala.
Cosecha propia
El principal desarrollo de la industria del transporte aéreo está asociado con el uso de aviones de producción nacional. El programa integral para el período de 2022 a 2030 prevé la recepción de 1.036 aviones y 764 helicópteros a las aerolíneas rusas. Esto incluyen la siguiente lista de futuros aviones: SSJ-NEW (142), MC-21-310 (270), Ilyusin Il-114-300 (70), Tupolev Tu-214 (70), Ilyusin Il-96-300 (12), Ladoga TVRS-44 (140), LET L-410 (178) y Baikal LMS-901 (154). En el área militar/logística: helicópteros Ansat (201) y helicópteros MIL Mi-8AMT/Mi-8MTV-1 (276), MIL Mi-171A2 (66), MIL Mi-171A3 (49), MIL Mi-38 (39), Kamov Ka-62 (90), Kamov Ka-32A11M (37), MIL Mi-26T (5) y Kamov Ka-226 (1). La implementación de tales planes a gran escala para el suministro de aviones nacionales debería permitir aumentar rápidamente la proporción de equipos de fabricación rusa en la flota de las aerolíneas rusas del 35,5% en 2022 al 81,3% en 2030.
El documento contiene indicadores de pronóstico de entregas de aeronaves por año. Con respecto a los aviones, lo primero que llama la atención es el retraso en el arranque. Se planea que los dos primeros SSJ-NEW se transfieran a los operadores en 2023, después de lo cual el ritmo de entregas debería alcanzar los 20 aviones por año. El documento enfatiza que ahora hay un alto grado de impricidad.la orto-dependencia de la industria aeronáutica nacional, sin embargo, se está trabajando activamente en SSJ-NEW destinado a la máxima sustitución de unidades y sistemas de importación, incluida la sustitución del motor principal por el PD-8 nacional. La certificación SSJ-NEW está programada para completarse en 2023. El ritmo declarado de producción de este avión es notablemente más bajo que el ritmo de ensamblaje alcanzado anteriormente del SSJ-100, por lo que es seguro decir que las capacidades de los fabricantes de aviones, incluida la producción de unidades y el ensamblaje final, no limitarán la producción de este revestimiento. En cuanto al motor PD-8, la situación también parece bastante optimista: la empresa Rybinsk «UEC-Saturn» ensambló una mayor cantidad de motores SaM146 con la misma dimensión. En cooperación con otras empresas de United Engine Corporation, se producirán 44 motores PD-8 anualmente.
La situación es diferente con el lanzamiento del avión MC-21-310, cuyas entregas están programadas para 2024 en la cantidad de seis aviones, seguido de un aumento en el número de aviones producidos a 12, 22, 36, 50 y 72 automóviles anualmente. La planta de aviación de Irkutsk, que forma parte de la Corporación Irkut, necesitará comprar máquinas, equipos y dispositivos adicionales para aumentar la producción, y lo más probable es que tenga que centrarse en los suministros de los fabricantes nacionales. La situación es similar para otras empresas que forman parte de cadenas de cooperación. En algunas áreas, no se esperan problemas: por ejemplo, en Rusia, se ha dominado la creación de líneas de producción para el ensamblaje de aviones. Pero en el equipo para la producción de unidades de gran tamaño a partir de materiales compuestos, todavía hay «puntos blancos». Los fabricantes de motores Perm necesitan aumentar la tasa de producción de motores PD-14 de 14 piezas en 2024 a 152 en 2030, mientras que se planea un aumento impresionante en la producción bajo el programa PS-90A, que hoy forma la base de la línea de producción UEC-Perm Motors, sin embargo, no en el marco del Programa Integral. El MC-21 es un avión ubicado en el nicho de mercado más popular, por lo que la tarea de dominar su producción a gran escala es una prioridad indudable para la industria aeronáutica nacional.
Los aviones Tupolev Tu-214, cuyas entregas deberían comenzar en 2023, se consideran una solución de nicho. Por un lado, el Tu-214 es una versión del avión básico Tu-204 con un mayor peso máximo de despegue. Gracias al suministro adicional de combustible, el avión puede realizar vuelos directos sin escalas desde Moscú a Khabarovsk. Incluso la modernización de complejidad moderada de la aeronave, que incluiría el uso de equipos de cabina más modernos, el reemplazo de redes de cable y una serie de otras mejoras, reduciría el peso de la estructura, lo que permitiría que la aeronave se utilizara para vuelos directos a otras ciudades del Lejano Oriente, incluidas Yuzhno-Sakhalinsk, Petropavlovsk-Kamchatsky, Anadyr y otras. Hasta que Irkut construya el MC-21-400 con mayor capacidad de asientos y alcance, el Tu-214 será el único avión ruso de pasillo único capaz de servir a estas rutas. Otro factor que influyó en la resurrección del Tu-214 es su independencia de importación. Es posible implementar la producción en serie de «Tushka» con bastante rapidez.
La decisión de restablecer la producción de aviones IL-96-300 plantea preguntas en la cantidad de dos aviones por año, a partir de 2025. Primero, a diferencia de la versión IL-96-400, activa Obra en la que se lanzó a mediados de la década pasada, el Serie 300 tiene una menor capacidad de asientos y peores indicadores en términos del costo de pasajeros-kilómetro. Completar el ROC, probar y certificar el IL-96-400 para 2025 es una tarea factible. Otra cuestión importante es que es poco probable que los doce aviones que se planea producir para 2030 cambien algo en la aviación civil nacional, pero el desarrollo de su operación será bastante costoso y problemático para las aerolíneas comerciales. Si no consideramos el escenario en el que todos los Il-96-300 se construirán en interés del Destacamento de Vuelo Especial «Rusia» y otros operadores «especiales», entonces la decisión de construir estos transatlánticos parece controvertida.
El estudio del programa de producción de componentes nacionales por año (el documento proporciona información sólo sobre los motores de las aeronaves) lleva a suponer que este conjunto de datos no está plenamente vinculado a los planes para la producción de aeronaves. Por lo tanto, la producción de motores PS-90 está planificada al nivel de veinte piezas por año. Sin embargo, veinte motores es un programa de producción para garantizar el ensamblaje de diez aviones Tu-214, sin proporcionar la reposición del grupo de motores de reemplazo. No se tienen en cuenta las necesidades del programa IL-96-300, que es de ocho motores por año.
Otra omisión de este tipo se ve en el programa para la producción de motores TV7-117ST. El documento indica solo la versión TV7-117ST-01 para el avión IL-114-300, mientras que se planea producir 26 motores para 12 aviones (se ensamblarán tantos Ilovs a partir de 2026). Pero no hay motores TV7-117ST-02 para el avión regional turbohélice Ladoga en la tabla, aunque 25 tableros por año requerirán al menos 54 motores al año.
El programa de producción de la empresa UEC-Klimov y su cooperación es otro desafío para el Programa Integral. Recuerde que de los 764 helicópteros que se planea producir para 2030, solo cinco helicópteros Mi-26T2/TS, un pequeño número de Ansats y el único Ka-226 tendrán motores no ensamblados en el UEC-Klimov. En cuanto al Ansat y Ka-226, esto está indicado por los planes para producir helicópteros en los años en que la producción del VK-650V para versiones remotorizadas aún no ha comenzado.
Más de 700 helicópteros bimotores, 210 aviones bimotores turbohélice, y esto es solo para operadores civiles. Los fabricantes de motores no tienen tiempo para oscilar, es urgente aumentar las capacidades de producción tanto de UEC-Klimov como de las empresas involucradas en suministros cooperativos. De los actuales aproximadamente 300 motores de helicóptero en 2023 será necesario hacer un gran avance a más de 460 productos, en 2024 para agregar casi un centenar de motores más.
Perspectivas aviación rusa
Una de las secciones del documento está relacionada con la evaluación de riesgos. Describe cuatro riesgos sistémicos: la eliminación de la flota existente de aeronaves debido a dificultades con el mantenimiento y el suministro de piezas de repuesto, el incumplimiento del cronograma para el suministro de aeronaves nacionales, la escasez de personal para la producción, operación y mantenimiento de aeronaves y los llamados riesgos externos. Un pesimista dirá que ejecutar el Programa Integral con tales riesgos es como declarar uno minúsculo con cuatro ases en sus manos. Un optimista dirá que cuanto más difícil sea la tarea, mayores serán las posibilidades de movilizar todos los recursos, porque no hay dónde retirarse.
Evaluación realista del futuro para hablar de un aspecto completamente diferente. Se necesita un programa amplio para asegurar que los organismos ajusten sus programas específicos sobre la base de ellos. El Ministerio de Transporte de Rusia y el Ministerio de Industria y Comercio de Rusia tienen tres meses para este trabajo. Es probable que durante este período se corrijan las inconsistencias en el número de motores y otros problemas. Los programas sectoriales incluirán actividades que apoyen la modernización acelerada de la producción y el desarrollo de los recursos humanos. Se señaló a la atención el problema del desarrollo de la industria del transporte aéreo al Consejo de Estado, dependiente del Comité de Transportes, del que se formó un grupo de trabajo sobre aviación civil. Es probable que el Consejo de Estado prepare sus recomendaciones sobre las cuestiones planteadas en el programa integral. Finalmente, hoy continúa la formación de un programa de órdenes civiles consolidadas para equipos de aviación, los parámetros de este documento aún no se han anunciado, pero deben considerarse como obligaciones de la industria de la aviación para producir aeronaves civiles. En consecuencia, actualmente la industria rusa podría repuntar en confianza que el Gobierno ruso en el desarrollo del transporte aéreo ha confiado en los aviones nacionales.
Integral Russian aviation program
Russian aeronautical industry seeks to be reborn
The Comprehensive Program for the Development of the Air Transport Industry of the Russian Federation until 2030 assumes that national airplanes will occupy more than 80% of the fleet of Russian airlines. The President of the Government of the Russian Federation, Mikhail Mishustin, at a meeting held on June 27, 2022 with the Deputy Prime Ministers, announced the adoption of the order of the Government of the Federation of Russia No. 1693-R of June 25 of 2022, which approved the Comprehensive Program for the Development of the Air Transport Industry of the Russian Federation until 2030. The need to create this document was declared during a meeting on the development of air transport and the construction of airplanes, chaired by Russian President Vladimir Putin on March 31, 2022. One of the instructions after the meeting suggested that the Government should approve a comprehensive program before June 1, 2022 and guarantee its implementation. According to the media, at the end of April, the Ministry of Transportation prepared the first version of the document, which, however, was sent for review. The second version of the program, sent to the government at the end of May, included a forecast that foresaw an increase in volume indicators.
The integrated program is a 30 -page document containing six annexes. The authors of the program evaluated the current situation in civil aviation and the aviation industry of Russia, including the forecast of the air transport volume, carried out an analysis of the airplane fleet, evaluated the prospects of maintaining their aircraft, identified priority types of national airplanes, due to which the fleet will be updated.
Volumetric indicators for transport on national and international routes, according to forecasts, should constantly increase. By 2022, the indicators are established by directive. Airlines will have to serve 90 million passengers in national airlines and 10 million passengers in international airlines (MVL). At the end of the program, VVL transport should reach 104.5 million passengers, and in MVL 11.6 million. Therefore, according to the document, the industry will restore the volume of traffic reached in 2021 in 111 million passengers, to increase it by 2029. The 2019 record figures (128 million passengers were transported) on the horizon of the program will remain unsurpassed.
The recovery of VVL volume indicators will occur at a moderate pace: 1.2% in 2023 to 3% in 2030. For the National Air Transport Market, such rates are not typical: since the beginning of the century, the industry It has shown much more intensive growth or, in times of crisis, a large -scale decrease. But even taking into account such rebound, the average rate of increase in passenger traffic was greater.
The authors of the document indicate that the nature of transport in national lines will not change radically: the configuration of the route network, which has been developed by 2021-2022, seems optimal. In total, 4,340 routes were served in the VVL in 2021, but around 480 of them provided 95% of the total national passenger traffic. However, the question about the configuration of the route network is still open: at the beginning of 2022, the participation of the Moscow Aviation Center was very large, so some of the passengers traveling from the starting points in the Urals or Siberia arrived in Moscow to continue the trip on international flights, or southern direction. Currently, Moscow is becoming a destination without exit: flights to the countries of the European Union (EU) have stopped and it is more profitable to fly south through regional centers.
Transport statistics second quarter
In 2022 the airports of the capital are losing passengers, but the Siberian aerostations, on the contrary, are increasing their passenger traffic. This trend, if current external factors persist, will be long term. A significant part of the document is dedicated to evaluating the current status of the Russian airline fleet and the impact of anti -Russian sanctions imposed by several hostile states. In April 2022, the Russian commercial airline fleet had 1,287 aircraft. Most of the fleet were passenger ships, there were 1,101 of them. Another 84 vehicles are trucks, 42 are business airplanes and 60 aircraft appear in the fleet in three federal state budget institutions, as well as in the Cosmos airline and do not really participate in commercial transport.
Two thirds of the fleet consists of foreign manufacturing aircraft. At the same time, they represent about 95% of the total passenger billing. This distribution is quite logical: foreign airplanes have superiority in the total capacity of seats and are operated in longer lines. In April 2022, Russian airlines operated 120 long -distance and 472 medium distance from foreign production, and not a single national transatlantic of this dimension. But in the short distance segments, regional machines and local airline aircraft, the superiority was on the side of the Russian and Soviet aircraft: 170 national short -distance aircraft against 23 foreign cars, 105 regional machines: 84 foreigners and 88 airplanes of local airlines, against 39.
A large number of airlines airlines, around 700 aircraft, belong to foreign lease companies. The most common form of aircraft transfer to the operational lease, in which at the end of the lease contract the aircraft are returned to the landlord. The sanctions imposed in the first quarter of 2022 against the Russia Federation implied a prohibition of the sale of airplanes and helicopters, which applied, among other things, to existing lease contracts. The landlords received instructions to terminate the contracts and confiscate the aircraft within one month until the end of March 2022. In addition, the sanctions affected two very sensitive areas of air transport: the prohibition of insurance and assessment of assets and the prohibition of The provision of maintenance and repair services of aircraft, components and systems. Shortly after the introduction of these restrictions, Western airplanes manufacturers notified Russian operators the cessation of support for their products and the cessation of the supply of spare parts. In this situation, those lease companies that were not obliged to break the agreements unilaterally, violating the existing agreements, demanded to return their assets earlier than expected, fearing a strong fall in their market value.
Russia’s air transport was found in a situation in which to follow the Western example and stop the operation of most of the aircraft fleet meant stopping industry activities, endangering the country’s territorial connectivity and drastically reducing the mobility of the population. Obviously, this approach was unacceptable for Russian civil aviation. An alternative solution is to refuse to return the plane, continue compliance with the obligations derived from the lease contracts, although in the transfer format of the lease payments in rubles at the current exchange rate to special accounts. It was this approach that assured the preservation of the vast majority of the airplanes in the fleet of the Russian transporters by April 2022. In turn, after the aviation authorities of several hostile countries decided to cancel the certificates of aircraft aircraft of the Russian airlines, a mass transfer of the fleet was made to the Civil Aircraft Registry of the Russian Federation, after which the Federal Air Transport Agency issued documents that confirmed the aircraft.
The adoption of emergency measures allowed to maintain a sufficient load capacity so that Russian airlines could continue to operate flights in national airlines, and even had some reserve that can be used in the fleet cannibalization format. This is due to the fact that the list of available international destinations has decreased markedly due to the closure of the airspace on hostile countries. But not all airplanes can fly to states that do not support sanctions: leased planes can be arrested in foreign airports.
Despite the sanctions, Russian airlines continue to actively operate foreign manufacturing planes. The Comprehensive Program pays attention to this problem: in particular, it is indicated that 241 aircraft maintenance organizations operate in Russia, including 34 that received approval documents in 2022. Regarding repairs, it is observed that for some types of aircraft, aircraft, The work is done exclusively abroad. For DHC-6 and DHC-8 aircraft, repair solutions in Russia are still complete, spare parts, blocks and assemblies can lead to the loss of aircraft of individual aircraft. However, the authors of the document evaluate this risk as moderate: by 2025, at least 70% of the current composition of the foreign fleet should remain in the wing.
Own harvest
The main development of the air transport industry is associated with the use of national production aircraft. The Comprehensive Program for the period from 2022 to 2030 provides for the reception of 1,036 aircraft and 764 helicopters to Russian airlines. This includes the following list of future airplanes: SSJ-New (142), MC-21-310 (270), Ilyusin IL-114-300 (70), Tupolev Tu-214 (70), Ilyusin Il-96-300 ( 12), Apartaga TVRS-44 (140), Let L-410 (178) and Baikal LMS-901 (154). In the military/logistics area: Ansat helicopters (201) and helicopters a thousand Mi-8amt/Mi-8MTV-1 (276), one thousand Mi-171a2 (66), one thousand Mi-171a3 (49), one thousand Mi-38 (39 ), Kamov KA-62 (90), Kamov Ka-32a11m (37), one thousand Mi-26t (5) and Kamov Ka-226 (1). The implementation of such large -scale plans for the supply of national airplanes should allow rapidly increasing the proportion of Russian manufacturing equipment in the fleet of Russian airlines of 35.5% in 2022 to 81.3% in 2030.
The document contains forecast indicators of aircraft per year. With respect to airplanes, the first thing that attracts attention is the delay in starting. It is planned that the first two SSJ-NEW are transferred to the operators in 2023, after which the delivery rate should reach 20 aircraft per year. The document emphasizes that there is now a high degree of impricity. The orthodependence of the national aeronautical industry, however, is actively working on SSJ-NEW intended for the maximum replacement of import units and systems, including the replacement of the main engine by The national PD-8. The SSJ-NEW certification is scheduled to be completed in 2023. The declared rhythm of production of this plane is remarkably lower than the assembly pace previously reached from the SSJ-100, so it is sure to say that the capabilities of aircraft manufacturers , including the production of units and the final assembly, they will not limit the production of this coating. As for the PD-8 engine, the situation also seems quite optimistic: the Rybinsk «UEC-SATURN» company assembled a greater amount of SAM146 engines with the same dimension. In cooperation with other United Engine Corporation companies, 44 PD-8 engines will be produced annually.
The situation is different with the launch of the MC-21-310 plane, whose deliveries are scheduled for 2024 in the amount of six planes, followed by an increase in the number of aircraft produced to 12, 22, 36, 50 and 72 cars annually . The Irkutsk aviation plant, which is part of the Irkut Corporation, will need to buy additional machines, equipment and devices to increase production, and most likely have to focus on the supplies of national manufacturers. The situation is similar for other companies that are part of cooperation chains. In some areas, no problems are expected: for example, in Russia, the creation of production lines for air assembly has been dominated. But in the equipment for the production of large units from composite materials, there are still «white points.» Motor manufacturers allow to increase the production rate of PD-14 engines 14 pieces in 2024 to 152 in 2030, while an impressive increase in production is planned under the PS-90A program, which today forms the base of the UEC-PERM Motors production line, however, not within the framework of the Comprehensive Program. The MC-21 is a plane located in the most popular market niche, so the task of dominating its large-scale production is an undoubted priority for the national aeronautical industry.
Tupolev Tu-214 aircraft, whose deliveries should begin in 2023, are considered a niche solution. On the one hand, the TU-214 is a version of the basic TU-204 plane with a higher weight of takeoff. Thanks to the additional fuel supply, the plane can make direct non -scales flights from Moscow to Khabarovsk. Even the modernization of moderate complexity of the aircraft, which would include the use of more modern cabin equipment, the replacement of cable networks and a series of other improvements, would reduce the weight of the structure, which would allow the aircraft to be used for Direct flights to other cities of the Far East, including Yuzhno-Sakhalinsk, Petropavlovsk-Kamchatsky, Anadyr and others. Until Irkut builds the MC-21-400 with the highest capacity of seats and scope, the TU-214 will be the only unique corridor plane capable of serving these routes. Another factor that influenced the resurrection of TU-214 is its import independence. It is possible to implement the «Tushka» serial production quite quickly.
The decision to restore the production of IL-96-300 aircraft raises questions in the amount of two planes per year, from 2025. First, unlike the IL-96-400 version, an active work in which it was launched to the mid-last decade, the 300 series has a lower capacity of seats and worst indicators in terms of the cost of passengers-kilometer. Completeing ROC, trying and certifying the IL-96-400 by 2025 is a feasible task. Another important issue is that it is unlikely that the twelve aircraft that is planned to produce by 2030 changes something in national civil aviation, but the development of its operation will be quite expensive and problematic for commercial airlines. If we do not consider the scenario in which all IL-96-300 will be built in the interest of the special «Russia» and other «special» operators, then the decision to build these transatlantics seems controversial.
The study of the national component production program per year (the document provides information only on aircraft engines) leads to assume that this data set is not fully linked to the plans for aircraft production. Therefore, the production of PS-90 engines is planned at the level of twenty pieces per year. However, twenty engines is a production program to guarantee the assembly of ten TU-214 aircraft, without providing the replacement of the group of replacement engines. The needs of the IL-96-300 program are not taken into account, which is eight engines per year.
Another omission of this type is seen in the TV7-117ST engines production. The document indicates only the version TV7-117ST-01 for the IL-114-300 aircraft, while it is planned to produce 26 engines for 12 aircraft (so many ILOVs will be assembled from 2026). But there are no TV7-117ST-02 engines for the TurboHélice Apartaga regional plane in the table, although 25 boards per year will require at least 54 engines a year.
The EUC-KLIMOV company production program and its cooperation is another challenge for the Comprehensive Program. Remember that of the 764 helicopters that are planned to produce by 2030, only five MI-26T2/TS helicopters, a small number of ANSATS and the only KA-226 will have not assembled engines in the EUC-KLIMOV. As for the ANSAT and KA-226, this is indicated by the plans to produce helicopters in the years in which the production of the VK-650V for tranotorized versions has not yet begun.
More than 700 bimotor helicopters, 210 Bimotores Turbohélice, and this is only for civil operators. Motor manufacturers do not have time to oscillate, it is urgent to increase the production capabilities of both EC-KLIMOV and the companies involved in cooperative supplies. Of the current approximately 300 helicopter engines in 2023 it will be necessary to make a great advance to more than 460 products, in 2024 to add almost a hundred more engines.
Russian aviation perspectives
One of the document sections is related to risk assessment. Describe four systemic risks: the elimination of the existing fleet of aircraft due to difficulties with the maintenance and supply of spare parts, breach of the schedule for the supply of national aircraft, the shortage of personnel for the production, operation and maintenance of aircraft and the so -called external risks. A pessimistic will say that executing the comprehensive program with such risks is like declaring a tiny with four aces in your hands. An optimistic will say that the more difficult the task is, the greater the possibilities of mobilizing all the resources, because there is nowhere to retire.
Realistic evaluation of the future to talk about a completely different aspect. A broad program is needed to ensure that organisms adjust their specific programs on their basis. The Ministry of Transportation of Russia and the Ministry of Industry and Commerce of Russia have three months for this work. It is likely that during this period the inconsistencies in the number of engines and other problems will be corrected. Sector programs will include activities that support the accelerated modernization of the production and development of human resources. The problem of the development of the air transport industry to the State Council, under the Transport Committee, which formed a working group on civil aviation was pointed out. The State Council is likely to prepare its recommendations on the issues raised in the Comprehensive Program. Finally, today the formation of a consolidated civil orders program for aviation equipment continues, the parameters of this document have not yet been announced, but should be considered as obligations of the aviation industry to produce civil aircraft. Consequently, currently the Russian industry could be confirmed in confidence that the Russian government in the development of air transport has trusted national airplanes.
Интегральная российская авиационная программа
Русская аэронавтика стремится возродиться
Комплексная программа развития воздушной транспортной промышленности Российской федерации до 2030 года предполагает, что национальные самолеты будут занимать более 80% парка российских авиакомпаний. Президент правительства Российской федерации Михаил Мишустин, на собрании, состоявшемся 27 июня 2022 года с заместителем премьер-министров, объявил о принятии приказа правительства Федерации России № 1693-R 25 июня 25 июня. 2022 года, которая одобрила комплексную программу для развития воздушной транспортной промышленности Российской федерации до 2030 года. Необходимость создания этого документа была объявлена во время заседания по развитию воздушного транспорта и строительства самолетов под председательством президента России. Владимир Путин 31 марта 2022 года. Одна из инструкций после встречи предположила, что правительство должно одобрить комплексную программу до 1 июня 2022 года и гарантировать ее реализацию. Согласно средствам массовой информации, в конце апреля Министерство транспорта подготовило первую версию документа, которая, однако, была отправлена для рассмотрения. Вторая версия программы, отправленная правительству в конце мая, включала прогноз, который предвидел увеличение объема.
Интегрированная программа представляет собой 30 -страничный документ, содержащий шесть приложений. Авторы программы оценили текущую ситуацию в гражданской авиации и авиационной индустрии России, включая прогноз объема воздушного транспорта, провели анализ флота самолета, оценили перспективы обслуживания своих самолетов, определили приоритетные типы национальных Самолеты, из -за которых флот будет обновлен.
Согласно прогнозам, объемные показатели транспорта на национальных и международных маршрутах должны постоянно увеличиваться. К 2022 году показатели устанавливаются директивой. Авиакомпаниям придется отбывать 90 миллионов пассажиров в национальных авиакомпании и 10 миллионов пассажиров в международных авиакомпании (MVL). В конце программы VVL Transport должен достигать 104,5 млн. Пассажиров и в 11,6 млн. MVL. Поэтому, согласно документу, отрасль восстановит объем трафика, достигнутый в 2021 году в 111 миллионах пассажиров, чтобы увеличить его к 2029 году. Рекордные данные 2019 года (128 миллионов пассажиров были доставлены) на горизонте программы останутся непревзойденными.
Восстановление показателей объема VVL будет происходить в умеренных темпах: 1,2% в 2023-3% в 2030 году. Для национального рынка воздушного транспорта такие ставки не являются типичными: с начала века отрасль, в которой она показала гораздо больше Интенсивный рост или, во времена кризиса, значительное снижение. Но даже с учетом такого отскока, средняя скорость увеличения пассажирского трафика была выше.
Авторы документа указывают, что характер транспорта в национальных линиях не будет радикально изменяться: конфигурация сети маршрутов, которая была разработана к 2021-2022 годам, кажется оптимальной. В общей сложности 4340 маршрутов были поданы в VVL в 2021 году, но около 480 из них предоставили 95% от общего национального пассажирского движения. Тем не менее, вопрос о конфигурации сети маршрутов по -прежнему открыт: в начале 2022 года участие Московского авиационного центра было очень большим, поэтому некоторые пассажиры, путешествующие с отправных точек в Урале или Сибирии, прибыли в Москву. Чтобы продолжить поездку на международных рейсах или на юге. В настоящее время Москва становится пунктом назначения без выхода: рейсы в страны Европейского Союза (ЕС) остановились, и более выгодно летать на юг через региональные центры.
Транспортная статистика во втором квартале
В 2022 году аэропорты столицы теряют пассажиров, но сибирские аэроскации, напротив, увеличивают их пассажирское движение. Эта тенденция, если текущие внешние факторы сохранятся, будет долгосрочной. Значительная часть документа посвящена оценке текущего статуса российского флота авиакомпаний и воздействия анти -русских санкций, наложенных несколькими враждебными государствами. В апреле 2022 года российский флот коммерческой авиакомпании имел 1287 самолетов. Большинство флотов были пассажирскими кораблями, их было 1101. Еще 84 автомобиля – это грузовики, 42 – это бизнес -самолеты, а 60 самолетов появляются в парке в трех федеральных государственных бюджетных учреждениях, а также в авиакомпании Cosmos и на самом деле не участвуют в коммерческом транспорте.
Две трети флота состоит из иностранных производственных самолетов. В то же время они составляют около 95% от общего количества пассажиров. Это распределение довольно логично: иностранные самолеты имеют превосходство в общей мощности мест и работают в более длинных линиях. В апреле 2022 года российские авиакомпании эксплуатировали 120 длинных и 472 среднего расстояния от иностранного производства, а не ни одной национальной трансатлантики этого измерения. Но в коротких расстояниях, региональных машинах и местных самолетах авиакомпании, превосходство было на стороне российского и советского самолета: 170 национальных самолетов с коротким расстоянием против 23 иностранных автомобилей, 105 региональных машин: 84 иностранца и 88 самолетов местных авиакомпаний , против 39.
Большое количество авиакомпаний авиакомпаний, около 700 самолетов, принадлежат иностранным арендованным компаниям. Наиболее распространенная форма передачи самолета в оперативный аренду, в которой в конце договора аренды самолеты возвращаются домовладельцу. Санкции, введенные в первом квартале 2022 года против Федерации России, подразумевали запрет продажи самолетов и вертолетов, которые, помимо прочего, применялись к существующим договорам аренды. Арендодатели получили инструкции по прекращению контрактов и конфисковать самолет в течение одного месяца до конца марта 2022 года. Кроме того, санкции затронули две очень чувствительные области воздушного транспорта: запрет страхования и оценки активов и запрет на положения услуг по техническому обслуживанию и ремонту самолетов, компонентов и систем. Вскоре после введения этих ограничений производители западных самолетов уведомили российских операторов о прекращении поддержки их продукции и прекращении поставки запасных частей. В этой ситуации те арендные компании, которые не были обязаны нарушать соглашения в одностороннем порядке, нарушая существующие соглашения, потребовали возвращения своих активов раньше, чем ожидалось, опасаясь сильного падения их рыночной стоимости.
Российский воздушный транспорт был обнаружен в ситуации, в которой можно следовать за западным примером, и остановить работу большей части самолетного парка означало прекращение деятельности отрасли, угрожая территориальной связи страны и резко снижение мобильности населения. Очевидно, этот подход был неприемлемым для Российской гражданской авиации. Альтернативное решение состоит в том, чтобы отказаться от возврата самолета, продолжить соблюдение обязательств, полученных из договоров аренды, хотя в формате передачи арендных платежей в рублях по текущему обменному курсу на специальные счета. Именно этот подход заверил сохранение подавляющего большинства самолетов в парке российских транспортеров к апреле 2022 года. В свою очередь, после того, как авиационные власти нескольких враждебных стран решили отменить сертификаты самолетов авиакомпании российских авиакомпаний, Массовый перевод флота был сделан в реестр гражданских самолетов Российской федерации, после чего Федеральное агентство воздушного транспорта выпустило документы, подтверждающие самолет.
Принятие чрезвычайных мер, позволивших поддерживать достаточную нагрузку, так что российские авиакомпании могли продолжать управлять рейсами в национальных авиакомпаниях и даже имели некоторый резерв, который можно использовать в формате каннибализации флота. Это связано с тем, что список доступных международных направлений заметно уменьшилось из -за закрытия воздушного пространства в враждебных странах. Но не все самолеты могут лететь в штаты, которые не поддерживают санкции: арендованные самолеты могут быть арестованы в иностранных аэропортах.
Несмотря на санкции, российские авиакомпании продолжают активно управлять иностранными производственными самолетами. Комплексная программа обращает внимание на эту проблему: в частности, указано, что 241 организация по техническому обслуживанию самолетов работает в России, в том числе 34, которые получили одобрения документов в 2022 году. Что касается ремонта, отмечается, что для некоторых видов самолетов, самолетов, работы выполняется исключительно за границей. Для самолетов DHC-6 и DHC-8 ремонтные решения в России все еще завершены, запасные части, блоки и сборки могут привести к потере самолетов отдельных самолетов. Тем не менее, авторы документа оценивают этот риск как умеренный: к 2025 году не менее 70% текущего состава иностранного флота должен оставаться в крыле.
Собственный урожай
Основное развитие отрасли воздушного транспорта связано с использованием национальных производственных самолетов. Комплексная программа за период с 2022 по 2030 год предусматривает прием 1036 самолетов и 764 вертолета для российских авиакомпаний. Это включает в себя следующий список будущих самолетов: SSJ-NEW (142), MC-21-310 (270), Ильусин IL-114-300 (70), Tupolev TU-214 (70), Ильусин IL-96-300 ( 12), Apartaga TVRS-44 (140), Let L-410 (178) и Baikal LMS-901 (154). В области военной/логистики: вертолеты ANSAT (201) и вертолеты тысяча Mi-8AMT/Mi-8MTV-1 (276), тысяча миомеров-171A2 (66), одна тысяча мио. -38 (39), Kamov KA-62 (90), Kamov KA-32A11M (37), одна тысяча MI-26T (5) и Камов Ка-226 (1). Внедрение таких крупных планов по поставке национальных самолетов должно позволить быстро увеличить долю российского производственного оборудования в парке российских авиакомпаний в 35,5% в 2022 году до 81,3% в 2030 году.
Документ содержит прогнозируемые показатели самолета в год. Что касается самолетов, первое, что привлекает внимание, – это задержка в запуске. Планируется, что первые два SSJ-новых передаются операторам в 2023 году, после чего скорость доставки должна достигать 20 самолетов в год. В документе подчеркивается, что в настоящее время существует высокая степень погружения. Однако правозащитность национальной аэронавтической промышленности активно работает над SSJ-новым, предназначенным для максимальной замены импортных единиц и систем, включая замену основного двигателя Национальный PD-8. Сертификация SSJ-NEW планируется завершить в 2023 году. Объявленный ритм производства этой плоскости удивительно ниже, чем темп сборки, ранее достигнутый из SSJ-100, поэтому обязательно скажут, что возможности производителей самолетов, в том числе Производство подразделений и окончательной сборки, они не будут ограничивать производство этого покрытия. Что касается двигателя PD-8, ситуация также кажется довольно оптимистичной: компания Rybinsk «UEC-Saturn» собрала большее количество двигателей SAM146 с тем же измерением. В сотрудничестве с другими компаниями United Engine Corporation будет производиться 44 двигателя PD-8.
Ситуация отличается с запуском самолета MC-21-310, поставки которых запланированы на 2024 год на сумму шести самолетов, а затем увеличение числа самолетов, производимого до 12, 22, 36, 50 и 72 автомобилей. ежегодно. Авиационный завод Irkutsk, который является частью корпорации Irkut, должен будет купить дополнительные машины, оборудование и устройства для увеличения производства, и, скорее всего, придется сосредоточиться на поставках национальных производителей. Ситуация аналогична для других компаний, которые являются частью цепочек сотрудничества. В некоторых областях не ожидается никаких проблем: например, в России было доминирует создание производственных линий для авиационной сборки. Но в оборудовании для производства крупных единиц из композитных материалов все еще есть «белые точки». Производители двигателей позволяют увеличить скорость производства двигателей PD-14 14 штук в 2024 году по 152 в 2030 году, в то время как в рамках программы PS-90A планируется впечатляющее увеличение производства, которая сегодня формирует основу производственной линии Motors UEC-Perm, однако, не в рамках комплексной программы. MC-21-это самолет, расположенный в самой популярной нише рынка, поэтому задача доминирования его крупномасштабного производства является несомненным приоритетом для национальной авиационной промышленности.
Самолет Tupolev TU-214, поставки которых должны начаться в 2023 году, считаются нишевым решением. С одной стороны, TU-214 является версией базовой плоскости TU-204 с большим весом взлета. Благодаря дополнительной подаче топлива самолет может совершать прямые нефалс -рейсы из Москвы в Хабаровск. Даже модернизация умеренной сложности самолета, которая будет включать в себя использование более современного салонного оборудования, замену кабельных сетей и ряд других улучшений, уменьшит вес структуры, что позволит использовать самолет для использования для Прямые рейсы в другие города Дальнего Востока, в том числе Южно-Сахалинск, Петропавловский-Камчатский, Анадир и другие. До тех пор, пока Иркут не создаст MC-21-400 с самой высокой пропускной способностью сидений и масштаба, TU-214 станет единственной уникальной плоскостью коридора, способной подавать эти маршруты. Другим фактором, который повлиял на воскресение TU-214, является его независимость импорта. Можно довольно быстро внедрить серийное производство «TUSCKA».
Решение восстановить производство самолетов IL-96-300 поднимает вопросы в количестве двух самолетов в год, с 2025 года. Во-первых, в отличие от версии IL-96-400, активной работой, в которой она была запущена в середине, В прошлом десятилетии серия 300 имеет более низкую мощность мест и худшие показатели с точки зрения стоимости пассажиров-километра. Завершение ROC, попытка и подтверждение IL-96-400 к 2025 году является возможной задачей. Другая важная проблема заключается в том, что маловероятно, что двенадцать самолетов, планируемый производить к 2030 году, меняет что -то в национальной гражданской авиации, но разработка его работы будет довольно дорогим и проблематичным для коммерческих авиакомпаний. Если мы не рассмотрим сценарий, в котором все IL-96-300 будут построены в интересах специальных «России» и других «специальных» операторов, то решение построить эту трансатлантику кажется спорным.
Изучение Программы производства национальной компонентов в год (документ предоставляет информацию только на авиационных двигателях) приводит к предположению, что этот набор данных не полностью связан с планами производства самолетов. Таким образом, производство двигателей PS-90 запланировано на уровне двадцати штук в год. Тем не менее, двадцать двигателей-это производственная программа, гарантирующая сборку десяти самолетов TU-214, не предоставляя замену группы запасных двигателей. Потребности программы IL-96-300 не учитываются, что составляет восемь двигателей в год.
Другое упущение этого типа можно увидеть в производстве двигателей TV7-117. В документе указывается только версия TV7-117ST-01 для самолета IL-114-300, в то время как он планируется производить 26 двигателей для 12 самолетов (так много ILOV будут собраны с 2026 года). Но нет никаких двигателей TV7-117ST-02 для регионального самолета TurboHélice Apartaga в столе, хотя для 25 досок в год потребуется не менее 54 двигателей в год.
Программа производства компании EUC-Klimov Company и ее сотрудничество являются еще одной проблемой для комплексной программы. Помните, что из 764 вертолетов, которые планируются производить к 2030 году, только пять вертолетов Mi-26T2/TS, небольшое количество ANSAT и единственное KA-226 не будут собирать двигатели в EUC-Klimov. Что касается ANSAT и KA-226, это указывает планы по производству вертолетов в годы, когда производство VK-650V для траноторизованных версий еще не началось.
Более 700 бимоторных вертолетов, 210 бимоторов Turbohélice, и это только для гражданских операторов. Производители двигателей не имеют времени на колебания, срочно увеличить производственные возможности как EC-Klimov, так и компаний, участвующих в кооперативных принадлежностях. Из нынешних приблизительно 300 двигателей вертолета в 2023 году необходимо будет значительно продвинуть более 460 продуктов, в 2024 году, чтобы добавить почти сто больше двигателей.
Российские авиационные перспективы
Один из разделов документа связан с оценкой риска. Опишите четыре системные риски: устранение существующего парка самолетов из -за трудностей с техническим обслуживанием и поставкой запасных частей, нарушением графика для поставки национальных самолетов, нехватка персонала для производства, эксплуатации и обслуживания самолетов и SO -названные внешние риски. Пессимистичный скажет, что выполнение комплексной программы с такими рисками – все равно, что объявление крошечной с четырьмя тузами в руках. В оптимистике скажет, что чем сложнее задача, тем больше возможностей мобилизации всех ресурсов, потому что негде уйти на пенсию.
Реалистичная оценка будущего, чтобы поговорить об совершенно ином аспекте. Требуется широкая программа, чтобы гарантировать, что организмы корректируют свои конкретные программы на своей основе. Министерство транспорта России и Министерства промышленности и торговли России имеет три месяца для этой работы. Вполне вероятно, что в течение этого периода несоответствия в количестве двигателей и других проблем будут исправлены. Секторные программы будут включать деятельность, которая поддерживает ускоренную модернизацию производства и развития человеческих ресурсов. Была указана проблема развития отрасли воздушного транспорта в Государственный совет, в рамках транспортного комитета, который сформировал рабочую группу по гражданской авиации. Государственный совет, вероятно, подготовит свои рекомендации по вопросам, поднятым в комплексной программе. Наконец, сегодня формирование консолидированной программы гражданских орденов для авиационного оборудования продолжается, параметры этого документа еще не объявлены, но должны рассматриваться как обязательства авиационной промышленности по производству гражданских самолетов. Следовательно, в настоящее время российская промышленность может быть уверена в уверенности в том, что российское правительство в развитии воздушного транспорта доверяло национальным самолетам.
PUBLISHER: Airgways.com DBk: Aviaport.ru / Airgways.com AW-POST: 202212060250AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®
United Airlines y Boeing acordarían mega-acuerdo compra aeronaves
United Airlines y The Boeing Company están cerca de un mega-acuerdo para la adquisición de hasta cien aeronaves Boeing 787 Dreamliner (100) que mejoraría el servicio de pasajeros en distancias de medio-largo rango. La aerolínea estaría inclinada por el Dreamliner a renovar su flota de fuselaje ancho, decantándose por el modelo americano en lugar del Airbus A350 europeo. El pedido del A350 podría convertirse al modelo A321NEO. El acuerdo podría cerrarse a fines de Diciembre 2022.
La compañía aérea con sede en Chicago se habría decantado por la selección en favor del 787 Dreamliner al formar parte de una flota de 66 unidades que ha estado operando durante alrededor de diez años. Un acuerdo eventual estaría seleccionado para incorporar órdenes y opciones en firme.
La nueva orden estaría enfocada para reemplazar la línea Boeing 767-300 (37) y Boeing 767-400 (16) que tienen una edad promedio de 27 y 21 años, respectivamente. Además, los Dreamliner apuntarían a reemplazar en una segunda etapa a los más veteranos Boeing 777-200 (74) que tienen una edad promedio de veinticuatro años.
Boeing produce actualmente tres variantes de la línea Dreamliner 787-8, 787-9 y 787-10. United Airlines podría elegir la versión más grande el Boeing 787-10 con mayores prestaciones, lo que lo colocaría en el nivel del Airbus A350-900 que se encontraba bajo análisis en United Airlines.
Reconversiones A350/A321NEO
Mientras tanto, United podría convertir las órdenes del constructor europeo del A350-900 (45) que están pendientes de entrega para cambiarlas a Airbus A321NEO de fuselaje estrecho, una aeronave ultra-exitosa con mejoras en el rango operativo (autonomía/alcance) superiores al Boeing 737-10 MAX. La aerolínea había ordenado originalmente A350-900 (25) en 2010, ampliando el pedide la versión más grande A350-1000 (35), pero en 2017, un nuevo giro actualizó las órdenes al A350-900 incrementando en 45 unidades. Las entregas, originalmente programadas para comenzar en 2020, solo se pospusieron hasta 2027. La opción de convertir el pedido al A321NEO implicaría saltarse el gran backlog para el modelo narrowbody del constructor Airbus Group.
United approximates mega-purchase to Boeing
United and Boeing would agree mega-agreement purchase aircraft
United Airlines and The Boeing Company are close to a mega-agreement for the acquisition of up to one hundred Boeing 787 Dreamliner (100) aircraft that would improve the passenger service in half-long range distances. The airline would be inclined by the Dreamline to renew its wide fuselage fleet, opting for the American model instead of the European Airbus A350. The A350 request could be converted to the A321neo model. The agreement could be closed at the end of December 2022.
The Chicago -based airline would have opted for the selection in favor of 787 Dreamliner to be part of a fleet of 66 units that has been operating for about ten years. An eventual agreement would be selected to incorporate orders and firm options.
The new order would be focused on replacing the Boeing 767-300 (37) and Boeing 767-400 (16) line that have an average age of 27 and 21 years, respectively. In addition, the Dreamliner would aim to replace in a second stage the most veteran Boeing 777-200 (74) who have an average age of twenty-four years.
Boeing acts actually variants of the Llínea Dreamliner 787-8, 787-9 and 787-10. United Airlines could choose the largest version Boeing 787-10 with greater performance, which would place it at the Airbus A350-900 level that was under analysis in United Airlines.
A350/A321NEO
Meanwhile, United could convert the orders of the European Contractor of the A350-900 (45) that are pending delivery to change them to Airbus A321neo of narrow fuselage, an ultra-exit aircraft with improvements in the operating range (autonomy/scope) higher than the Boeing 737-10 Max. The airline had originally ordered A350-900 (25) in 2010, expanding the most large version A350-1000 (35), but in 2017, a new turn updated the orders to the A350-900 increasing in 45 units. The deliveries, originally scheduled to begin in 2020, were only postponed until 2027. The option of converting the order to the A321neo would imply skipping the great backlog for the Narrowbody model of the builder Airbus Group.
PUBLISHER: Airgways.com DBk: United.com / Boeing.com / Airgways.com AW-POST: 202212060208AR OWNERSHIP: Airgways Inc. A\W A I R G W A Y S ®